How to Set Up a Trust for a Parent: Steps, Costs and Medicaid Rules (2026)
Medicaid trust rules checked against 42 U.S.C. § 1396p, October 2026. Prices are published figures, not quotes. Not legal advice.
In this guide
- How a trust works, in plain terms
- Revocable or irrevocable: the choice that matters most
- How to set up a trust: step by step
- How much does it cost to set up a trust?
- Trusts and Medicaid: what protects savings and what doesn’t
- Setting up a trust for a parent: who can sign
- When the successor trustee takes over
- Mistakes that undo a trust
- Getting the right help
- FAQs
A trust can keep a parent’s affairs out of probate, let a family member step in smoothly if they can’t manage, and, set up the right way and early enough, protect savings from nursing home costs. Here is how setting one up works, what it costs, and the Medicaid rules that decide whether it helps.
Key takeaways
- A trust is a legal arrangement in which a trustee holds property for the beneficiaries, under rules the person setting it up (the grantor) writes down
- A revocable living trust avoids probate and makes incapacity easier, but it gives no protection from Medicaid: everything in it counts as your parent’s money
- An irrevocable trust that can never pay principal back to your parent can protect savings from nursing home costs, but only after the 5-year look-back has passed
- Setting one up costs from about $400 online to $1,500–$4,000 with an attorney for a typical living trust (LegalZoom’s 2026 price guide). Medicaid trusts usually cost more
- A trust only controls what is moved into it. An unfunded trust is the most common and most expensive mistake
- Your parent must sign as grantor while they have capacity. An agent under a power of attorney can create a trust only if the document expressly allows it
Quick answer
How do you set up a trust?
To set up a trust, decide what it should do (avoid probate, plan for incapacity or protect assets for Medicaid), choose revocable or irrevocable, pick a trustee and a successor trustee, and have the trust document drafted and signed, usually before a notary. Then fund it: retitle bank and brokerage accounts in the trustee’s name, deed real estate to the trust, and update beneficiary designations where appropriate. A will that pours leftover assets into the trust completes the plan. Online services start around $400; an attorney typically charges $1,500 to $4,000 for a living trust, more for a Medicaid asset protection trust.
How a trust works, in plain terms
Every trust has three roles, and one person can hold more than one of them:
- The grantor (also called the settlor or trustor) creates the trust and puts property into it. For a parent’s trust, that is your parent
- The trustee manages the property under the trust’s rules. With a living trust, your parent is usually their own trustee while they are well
- The beneficiaries receive the benefit: your parent during their life, then the people they name, often their children
- The successor trustee takes over if the trustee dies or can no longer manage. This is often an adult child, and it is the role that makes a trust so useful for later life
A trust is not a bank account. It is a written set of rules, and it only controls property that has been legally transferred to the trustee. That transfer, called funding, is a separate step from signing the document.
An ElderlyDaily original
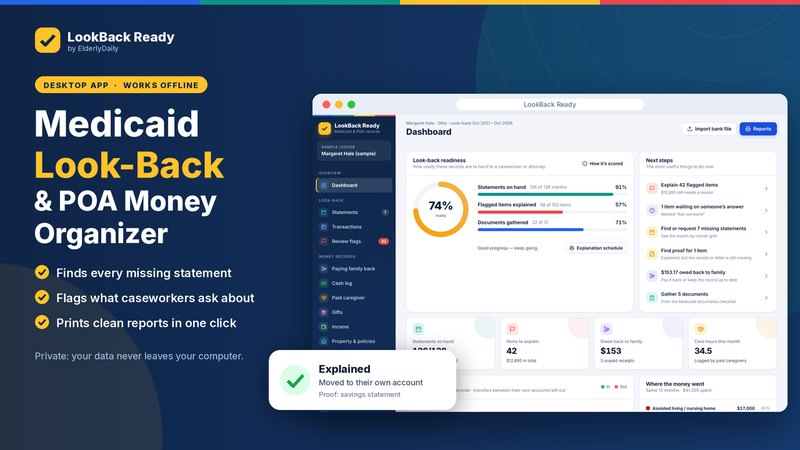
Getting a parent’s records ready for the look-back?
LookBack Ready: Medicaid Look-Back & POA Money Organizer
- A month-by-month checklist of every statement, for every account, closed ones included
- Imports bank download files and flags cash, checks, transfers and payments to family
- Explain each item once, with the proof and where it’s kept
One-time purchase · Instant download · Desktop app · Windows & Mac · works offline
Revocable or irrevocable: the choice that matters most
The main question is whether your parent wants to keep control (revocable) or needs protection from long-term care costs (irrevocable). You can’t have both in one trust.
| Revocable living trust | Irrevocable Medicaid asset protection trust | |
|---|---|---|
| Can your parent change or cancel it? | Yes, at any time while they have capacity | Generally no |
| Avoids probate for assets in it | Yes | Yes |
| Successor trustee steps in at incapacity | Yes | Yes |
| Counts as your parent’s money for Medicaid | Yes, all of it | Principal no, if it can never be paid back to them; income that can be paid to them, yes |
| Look-back penalty | None (it is still their money) | Moving assets in is a transfer: protected only after 5 years |
| Protects from nursing home costs | No | Yes, once outside the look-back |
| Typical cost to set up | About $400 online; often $1,500–$4,000 with an attorney | Usually more than a living trust; drafted by an elder law attorney |
A living trust does not protect savings from Medicaid
This is the most common misunderstanding. Federal law says the whole of a revocable trust counts as the person’s own resources for Medicaid (42 U.S.C. § 1396p(d)(3)(A)). It is a good tool for probate and incapacity, not for long-term care costs.
How to set up a trust: step by step
The same steps apply whether your parent uses an online service or an attorney. The legal work is in steps 3 and 5; the family work is in steps 4 and 6.
- 1
Decide what the trust must do
Avoid probate? Make it easy for a child to take over if memory fails? Protect savings from nursing home costs? Provide for a disabled relative? Write the goal down: it decides the type of trust and how much legal help you need.
- 2
Choose the type
A revocable living trust for probate and incapacity planning; an irrevocable trust for Medicaid asset protection, or for a family member on benefits. Medicaid trusts must be drafted to your state’s rules, so use an elder law attorney.
- 3
Pick the trustee and a successor
Your parent is usually the first trustee of a living trust. Name at least one successor, someone organized and trusted by the rest of the family. For an irrevocable Medicaid trust, your parent normally cannot be the trustee.
- 4
List every asset and how it is titled
Bank and brokerage accounts, the home and any other real estate, life insurance, retirement accounts, vehicles and valuables, with the account numbers and who owns each one now. This list is what the funding step works from.
- 5
Have the document drafted and signed
The grantor signs the trust, usually in front of a notary, and some states have extra signing rules. Your parent must have the capacity to understand what they are signing. Most plans add a pour-over will that moves anything left outside the trust into it at death.
- 6
Fund the trust
Retitle bank and brokerage accounts in the trustee’s name, record a new deed putting the home in the trust, and assign other property. Retirement accounts usually stay in your parent’s name with updated beneficiaries, because retitling one can count as a taxable withdrawal. Ask before changing any of them.
- 7
Keep records and review
Keep the signed trust, the funding records and a current asset list together. Review the plan after a death, a move to another state, a large change in savings or a diagnosis that may lead to long-term care.
How much does it cost to set up a trust?
There is no official price list, and fees vary by state and complexity. Published figures give a fair sense of the range:
- Online services: LegalZoom’s 2026 price guide puts DIY and online living trusts at about $400 to $1,000. Trust & Will’s trust plan starts at $499, plus a $49 yearly membership (its pricing page, October 2026)
- An attorney-drafted living trust: typically $1,500 to $4,000, and over $5,000 for complex estates, according to the same LegalZoom guide
- Hourly rates: the average will and trust lawyer charges around $370 an hour, according to Clio data cited in that guide. Many estate planning attorneys charge a flat fee for a standard trust package instead, so ask
- Medicaid asset protection trusts: these are drafted for your state’s Medicaid rules and usually cost more than a basic living trust. Get a written flat-fee quote that says what is included
- Funding: county fees to record a new deed, and sometimes a lawyer’s time to retitle accounts. Ask whether funding is included in the quote
An irrevocable trust also has running costs: it is a separate taxpayer, and a trust with gross income of $600 or more generally has to file its own federal return, Form 1041.
When an online trust is enough, and when it isn’t
An online living trust can work for a single parent with a home and a few accounts in one state, no disabled beneficiaries and no Medicaid plans. Use an attorney if long-term care is likely, if there is property in more than one state, a business or a blended family, or if anyone in the family is likely to object.
Trusts and Medicaid: what protects savings and what doesn’t
Federal law sets out how Medicaid treats a trust made with a person’s own money (42 U.S.C. § 1396p(d)):
- Revocable trust: everything in it counts as your parent’s resources. Payments to them count as income
- Irrevocable trust: any part that could be paid to your parent, under any circumstances, still counts. A trust that can pay your parent its income, but never its principal, protects only the principal
- The part that can never be paid back is treated as a gift made on the day it was put in the trust. That makes it subject to the 5-year look-back: moved in more than 60 months before a long-term care application, it is protected; moved in later, it can cause a penalty
Three kinds of trust are exceptions under the same law, and none of them is a way to keep savings for the family:
- A special needs trust for a disabled person under 65, which must repay the state from what is left at death
- A qualified income trust (often called a Miller trust), used in some states when a person’s income is just over the limit for nursing home Medicaid
- A pooled trust run by a nonprofit for disabled people, with each person’s money in a separate account
Timing is everything with a Medicaid trust. Started five years before care is needed, it can protect a home or savings. Started six months before, it mostly creates a penalty. If care may be needed soon, see an elder law attorney before moving anything, and read about exempt transfers and what happens to the house.
An ElderlyDaily original
LookBack Ready: Medicaid Look-Back & POA Money Organizer
$49One-time purchase · Instant download · Desktop app · Windows & Mac · works offline
Setting up a trust for a parent: who can sign
Your parent has to set up a trust of their own money themselves, as grantor, and must understand what they are signing. You can help find the attorney, gather the asset list and come to the meetings, but the attorney will want to speak with your parent, often alone, to make sure the decisions are theirs.
If your parent can no longer sign, an agent under a power of attorney can create or fund a trust only if the power of attorney expressly grants that authority. Under the Uniform Power of Attorney Act, creating, amending or revoking a trust is one of the powers that must be written in (Utah Code § 75A-2-201). See our guide to the durable power of attorney. Without that power, the usual route is a court.
A trust fund for a parent, set up with your own money, is a different thing. If children pool money in a trust for a parent’s benefit, the trust is made with the children’s money, not the parent’s, so the Medicaid trust rules above don’t apply in the same way. How the money is paid out still matters: cash handed to a parent on SSI or Medicaid can reduce their benefits, which is why trustees usually pay bills and providers directly. Ask an elder law attorney to draft it.
When the successor trustee takes over
If your parent can no longer manage, or dies, the successor trustee steps in under the terms of the trust, without a court case for the assets in it. In practice that means:
- Gathering the trust document, the death certificate or a doctor’s letter confirming incapacity, as the trust requires
- Showing banks a certification of trust (a short summary many states allow instead of the whole document)
- Keeping the trust’s money separate from your own, and a record of every payment
- After a death: paying final bills, filing tax returns, and distributing to the beneficiaries as the trust says, while keeping them informed
A trustee is a fiduciary, with the same duties as an agent under a power of attorney: act for the beneficiaries, not yourself, and keep good records. Assets outside the trust, and anything the will covers, still go through the executor.
An ElderlyDaily original
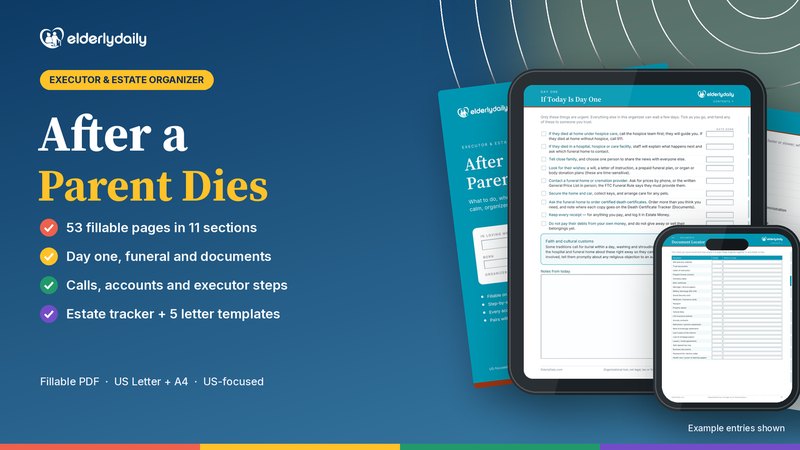
After a Parent Dies: Executor & Estate Organizer
$24One-time purchase · Instant download · Fillable PDF · 53 pages · US Letter + A4
Mistakes that undo a trust
- Never funding it. A signed trust with nothing in it doesn’t avoid probate. Check every account title after signing
- Assuming a living trust protects against nursing home costs. It doesn’t. Only an irrevocable trust set up outside the look-back does
- Waiting too long for a Medicaid trust. Funding it within five years of applying can cause a penalty instead of protection
- Retitling a retirement account into the trust. This can count as a full taxable withdrawal. Change the beneficiary designation instead, with advice
- Naming one child without telling the others. Surprises are where family disputes, and legal fees, start. Share at least who the trustees are
- Forgetting to update it after a move to another state, a divorce or a death in the family
Getting the right help
For a Medicaid trust, look for an attorney who practises elder law in your parent’s state: the National Academy of Elder Law Attorneys has a directory of members. For a simple living trust, an estate planning attorney or a reputable online service may be enough. If money is tight, LawHelp.org lists free legal aid by state.
Not legal advice
This guide explains how trusts generally work and how federal Medicaid law treats them. State rules differ on signing, deeds, taxes and Medicaid, and only an attorney licensed in your parent’s state can say which trust suits them.
Frequently asked questions
How much does it cost to set up a trust?
For a living trust, about $400 to $1,000 through an online service and typically $1,500 to $4,000 with an attorney, according to LegalZoom’s 2026 price guide. Complex estates and Medicaid asset protection trusts cost more. Ask whether funding the trust is included.
How much do lawyers charge to set up a trust?
Many charge a flat fee for a standard trust package, often in the $1,500 to $4,000 range for a living trust. Those who bill hourly charge around $370 an hour on average for wills and trusts work, according to Clio data cited by LegalZoom. Rates are higher in big cities and for elder law work involving Medicaid.
Can I set up a trust without a lawyer?
Yes. Online services and state forms can produce a valid revocable living trust for a simple estate. For an irrevocable Medicaid trust, a special needs trust or anything involving several states or a business, use an attorney: a drafting mistake can cost far more than the fee.
Does a living trust protect assets from Medicaid?
No. Federal law counts everything in a revocable trust as the person’s own resources. Only an irrevocable trust that can never pay principal back to the person can protect assets, and only after the 5-year look-back period has passed.
Can I put my parent’s house in a trust?
Your parent can, by signing a new deed to the trustee and recording it. With a living trust, that avoids probate but doesn’t protect the house from Medicaid. With an irrevocable trust, the transfer starts the 5-year look-back clock. There can also be property tax and income tax effects, so get advice first.
What is the difference between a will and a trust?
A will takes effect only at death and usually goes through probate court. A living trust works during life too, lets a successor trustee take over if your parent can’t manage, and passes the assets in it without probate. Most trust plans include a short pour-over will as a safety net.
How long does it take to set up a trust?
Drafting and signing can take days online or a few weeks with an attorney. Funding takes longer: allow several weeks for banks to retitle accounts and the county to record a deed.
Sources
- U.S. Code (Cornell LII). 42 U.S.C. § 1396p — transfers of assets: the look-back date, the penalty period and exempt transfers
- Utah Code (Uniform Power of Attorney Act). § 75A-2-201 — authority that requires a specific grant: trusts, gifts, survivorship, beneficiary designations
- LegalZoom (updated March 2026). How much does a living trust cost? 2026 price guide — online and attorney price ranges; Clio hourly-rate data
- Trust & Will. Pricing — trust plan from $499, plus a $49 yearly membership (read October 2026)
- IRS. Instructions for Form 1041 — who must file
- CMS. State Medicaid Director Letter #06-018 — Deficit Reduction Act of 2005 transfer-of-assets provisions
